Perpetual funding and open interest: compare the same quantity on the same clock
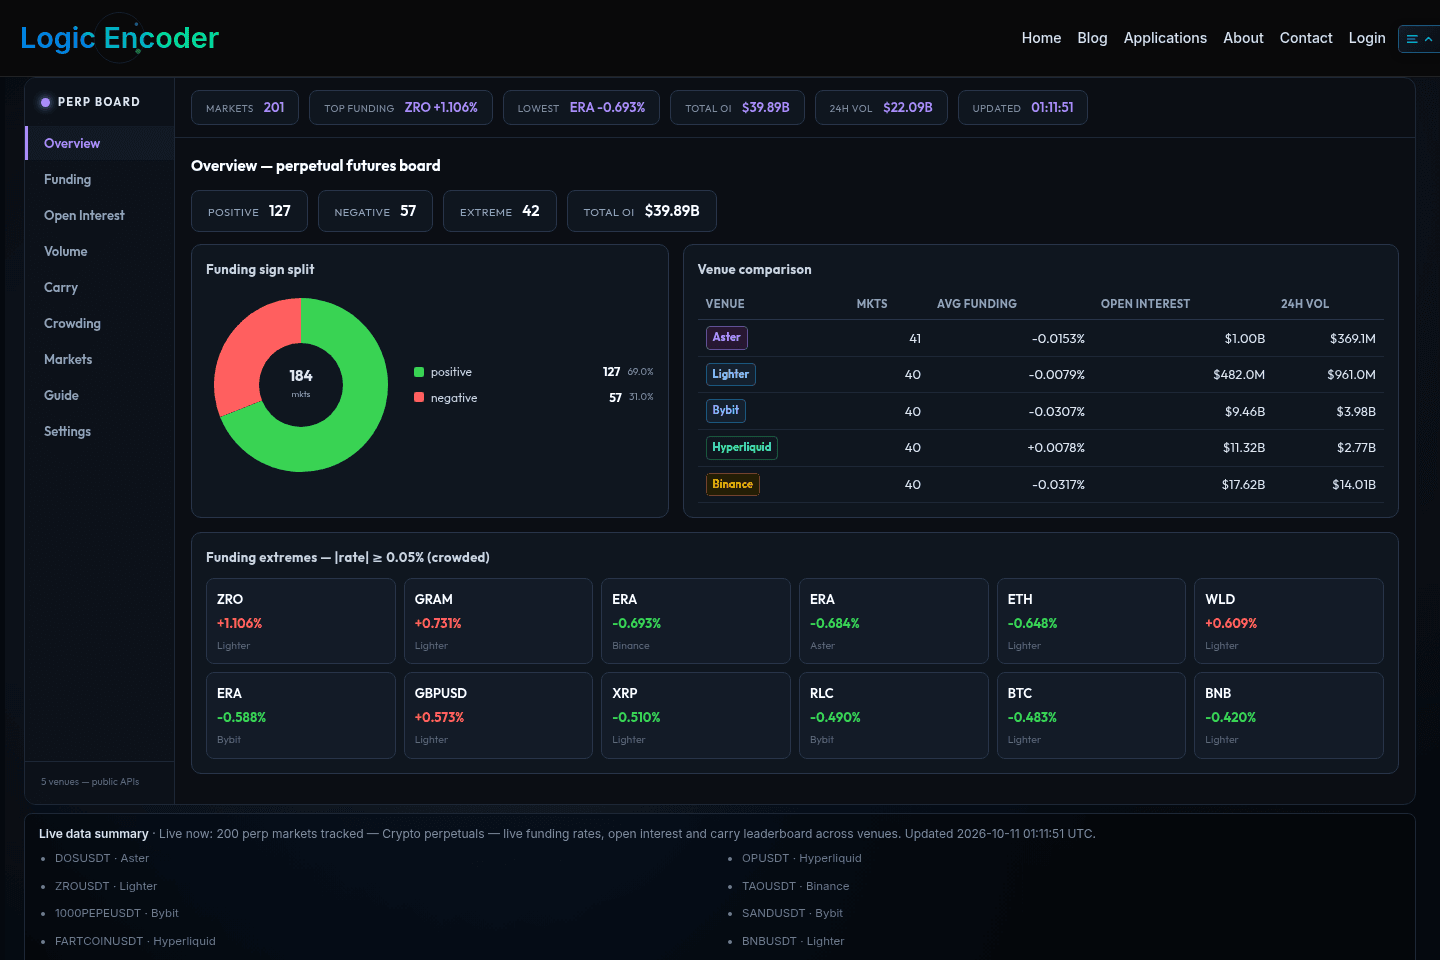
The Crypto Perp Board brings funding and open-interest observations together so you can inspect differences between available venues. A useful comparison begins with three questions: which contract is this, what interval does the funding rate describe, and what unit is used for open interest?
In this guide
- Perpetual funding and open interest: compare the same quantity on the same clock
- Funding is a payment mechanism, not a count of bullish traders
- Estimated, current, and settled rates must stay distinct
- Open interest is a stock; volume is a flow
- Read Carry and Crowding as dashboard measures
- A useful comparison workflow
- Questions readers often ask
The board provides Overview, Funding, Open Interest, Volume, Carry, Crowding, Markets, Guide, and Settings. Venue availability should be read from the current snapshot, rather than assuming an old article’s two-venue description is exhaustive. Missing data are not a zero rate or zero open interest.
Funding is a payment mechanism, not a count of bullish traders
Funding payments help keep a perpetual contract aligned with its reference market. Under the usual sign convention, positive funding means longs pay shorts; negative funding reverses the direction. The contract’s venue rules determine the calculation, settlement interval, and which positions are eligible at settlement.
For a linear contract, a simplified illustration is position value × funding rate. At a hypothetical 10,000 USDT position value and a 0.01% rate, the payment magnitude is 1 USDT. This is an example, not a live board observation. Margin is not the same as position value: using a smaller margin does not automatically make the funding payment smaller for the same position.
Rate intervals can differ by contract and venue. One hourly rate is not directly comparable with one eight-hour rate. When the board normalises a source to an eight-hour equivalent, that is a comparison convention, not a claim that the venue settles only every eight hours. A simple annualised rate extrapolates a current rate; it is not a promised year’s return.
Estimated, current, and settled rates must stay distinct
A rate for the next settlement can change before that settlement. A last settled rate is historical. A source’s current estimate can be useful, but it should not be described as a confirmed payment. Check the source field, any estimate marker, interval, and next-settlement time.
The board includes source-specific handling for different venues, including hourly-equivalent comparisons and estimated funding where appropriate. Always use the current labels and the venue’s contract specification when the distinction matters. A smooth refresh does not prove that the underlying rate was newly settled.
Why a rate ratio can mislead
Suppose two hypothetical eight-hour rates are −0.153% and −0.002%. The absolute ratio is 76.5, not 15. The signed difference is −0.151 percentage points. Neither quantity means that one venue has 76.5 times as many short traders. Funding is a rate arising from contract pricing and venue rules, not a population count.
Ratios also become unstable when the denominator is close to zero. In that situation, compare percentage-point differences, actual payment magnitudes, time intervals, and liquidity instead of making a dramatic “times larger” claim.
Open interest is a stock; volume is a flow
Open interest describes outstanding contract exposure at a point in time. Volume describes trading over an interval. High volume can occur while open interest stays broadly unchanged because positions are changing hands or opening and closing within the window.
Check whether open interest is stated in contracts, base-asset units, or a converted quote-currency value. Converting units with a price can make the reported value change even when the contract count changes little. Two venue totals can also cover different contract sets, so a larger displayed aggregate is not automatically evidence of stronger conviction.
| Observation | What it supports | What it does not prove |
|---|---|---|
| Strong negative funding | A negative rate under the displayed venue convention | An inevitable short squeeze |
| Rising open interest | More outstanding exposure in the stated units | The identity or direction of every trader |
| Large 24-hour volume | A lot of trading over that window | Persistent new positions of the same size |
| Large funding difference | A rate comparison worth investigating | A cost-free or risk-free cross-venue trade |
Read Carry and Crowding as dashboard measures
The Carry view presents a derived funding perspective. Its assumptions matter: holding periods, rate persistence, costs, and execution are not settled by an attractive number. Crowding combines observable quantities into a dashboard score; it is not an exchange-certified probability of a squeeze or a liquidation forecast.
Use these views to prioritise inspection. Then verify the contract, units, source age, and venue rules. Do not turn a score into an event prediction merely because it sits beside real market observations.
A useful comparison workflow
- Select matching underlying assets and comparable contract types.
- Check source age and whether the rate is estimated, current, or settled.
- Compare the funding interval or the board’s stated normalisation.
- Read open interest in its stated unit and volume in its stated time window.
- Inspect the venue’s contract details and actual costs before making an execution calculation.
- Treat Carry and Crowding as derived aids, and keep their assumptions attached to any conclusion.
Questions readers often ask
Does negative funding guarantee a squeeze?
No. It establishes a negative funding observation under a contract’s rules. Future price movement needs additional evidence and remains uncertain.
Is the displayed APR what I will earn?
No. Extrapolating a current rate assumes persistence that may not occur and does not settle execution, fees, or other position costs.
Why can open interest rise while volume falls?
They measure different things: outstanding exposure at a point in time versus trading during a window. Their units and clocks must be checked separately.
Is funding charged on margin or the entire position?
Check the contract rules. For a linear contract, the relevant position value can be much larger than the margin posted.
Bybit’s funding-fee documentation provides a primary explanation of its settlement mechanism. Use each venue’s current contract specification for an actual calculation; this guide’s numerical examples are explicitly hypothetical.